AI in Credit Scoring: Why Traditional Models Are Failing Today's Borrower
Artificial Intelligence

AI in Credit Scoring: Why Traditional Models Are Failing Today's Borrower

Author: Nishant Bijani
Make us preferred on Google
Read time:7 MinUpdated:September 26, 2025

TL;DR

  • What it is: AI credit scoring uses machine learning to estimate how likely a borrower is to repay, using credit bureau data plus other data such as bank transactions and rent payments.
  • Who it helps: People with thin or no credit files. The CFPB estimated in 2015 that about 45 million US adults were credit invisible or unscorable.
  • The rules: US lenders must give specific reasons for every denial, including when a complex model makes the decision.
  • The risk: AI can reduce or increase bias. Test outcomes across groups and keep explanations for every decision.
  • The result: More approvals among thin-file applicants at the same risk, when the model is validated against the lender's own loan history.

What Is AI Credit Scoring?

AI credit scoring uses machine learning to estimate how likely a borrower is to repay a loan. It uses traditional credit bureau data plus other data, such as bank account transactions shared with consent, income stability, and rent or utility payments. It can score people with thin credit files, but lenders must still explain each decision and test the model for bias.

The CFPB estimated in 2015 that about 45 million US adults were either credit invisible (26 million) or had files too thin or too old to score (19 million). Many of them pay rent and bills on time, but traditional scores cannot see it.

Why Traditional Credit Scoring Models Are Failing Borrowers

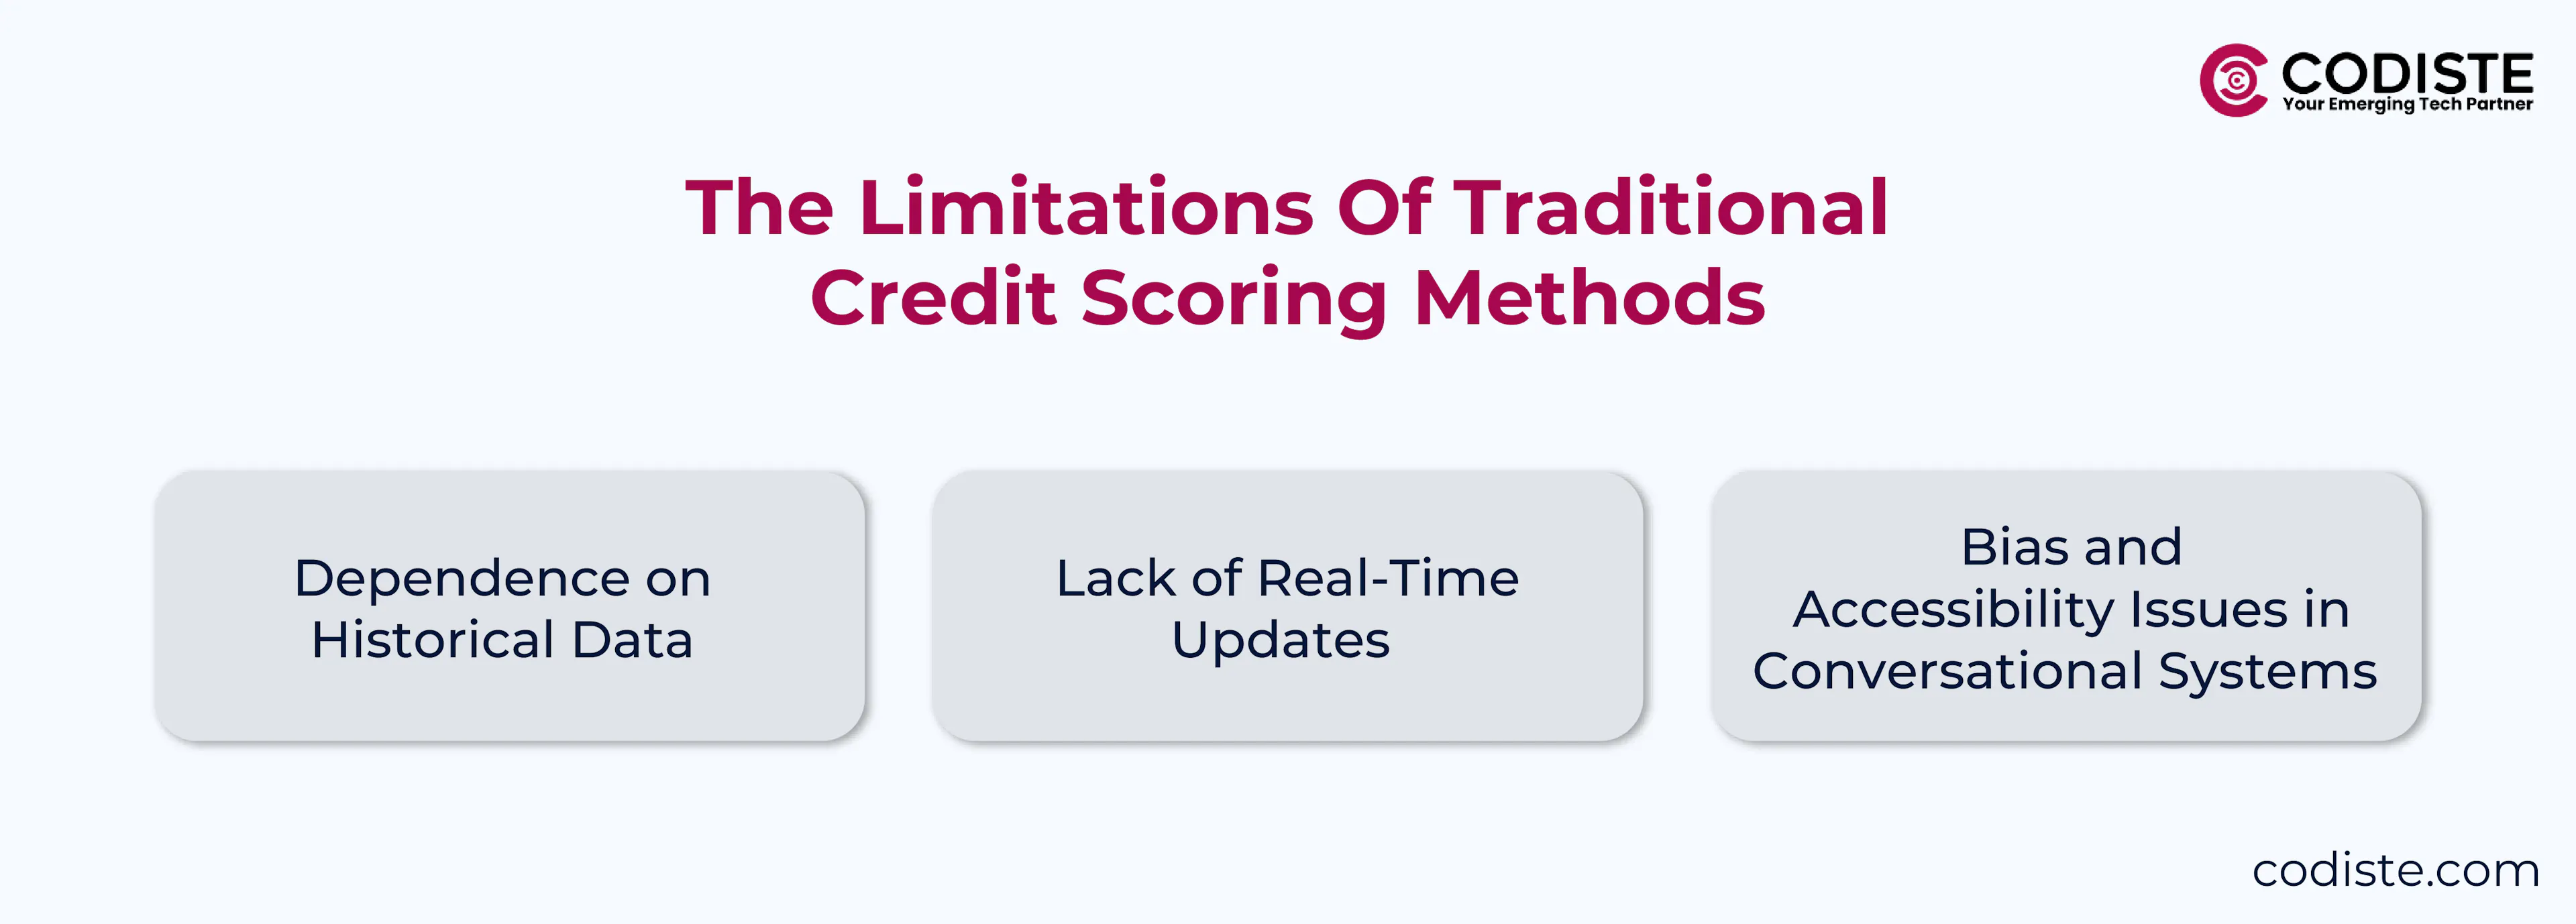
The limitations of traditional credit scoring methods

Traditional credit scoring relies on credit bureau history: cards, loans and repayment records. The FICO score, introduced in 1989, is built mainly on that history, so people without it are hard to score.

Here is what legacy approaches miss:

Limited data sources

  • Payment history limited to traditional credit products
  • Rent, utility and subscription payments often not counted
  • Gig economy and irregular income hard to read

Groups that are often under-scored

  • Young professionals with thin credit files but stable income
  • Gig workers with irregular income
  • Recent immigrants with no US credit history
  • People who mainly use cash or debit

How AI Credit Scoring Improves Risk Assessment

AI credit scoring looks at more data and finds patterns that simple scorecards miss. The model learns from past loans which signals predict repayment.

Cash-flow and behavior signals

  • Bank transaction data that shows cash flow stability
  • Consistent bill payment history
  • Income stability for gig workers and freelancers
  • Savings behavior over time

Alternative data that lenders commonly use

  • Rent, utility and telecom payment history
  • Bank cash-flow data shared with consent through open banking
  • Verified employment and income

Every input must be explainable in an adverse action notice and checked so it does not act as a proxy for a protected trait. Data such as social media activity or device usage is hard to explain and risky for credit decisions, so it is best avoided.

Dynamic risk modeling: AI models can be updated as new data arrives, so risk profiles reflect a borrower's current situation rather than an old snapshot. Every model update must be validated before use.

Is AI Credit Scoring Biased?

It can be. Models can pick up bias from historical data or from inputs that stand in for protected traits, such as location. When built and tested carefully, AI can widen access to credit without unfair results, but bias reduction must be tested, not assumed.

What US Rules Apply to AI Credit Scoring?

In the US, the Equal Credit Opportunity Act and Regulation B require lenders to give applicants the specific principal reasons when credit is denied. A general statement such as "you did not meet our scoring standard" is not enough, and the same rule applies when the decision comes from a complex model. A model that cannot produce clear reasons is not usable for credit decisions.

A compliant framework includes:

  • Model interpretability that meets fair lending rules
  • Adverse action notices with specific reason codes
  • Regular bias testing across protected groups
  • A documented audit trail for regulators

What Results Can Lenders Expect?

Results depend on your data and your current model, so measure them on your own loans. Run the AI model in parallel with your current scorecard on a test group, and compare:

  • Approval rate, especially for thin-file applicants
  • Default and charge-off rates at the same approval level
  • Decision time and manual review volume
  • Outcomes across protected groups

Lenders typically look for more approvals at the same risk, earlier warning of borrowers in distress, and less manual underwriting.

How Generative AI Helps in Credit Risk Management

Generative AI does not replace the credit model. It supports the work around it in credit risk management.

  • Plain-language explanations of credit decisions for applicants and staff
  • Synthetic data and scenarios for stress testing and model validation
  • Draft risk reports and regulatory narratives for review
  • Guidance for declined applicants on how to improve

How to Implement AI Credit Scoring

Step 1: Prepare the data

  • Audit data sources for quality and completeness
  • Build secure pipelines for alternative data, with consent records
  • Set up model monitoring and validation

Step 2: Run a pilot

  • Start with one segment, such as thin-file applicants
  • Score in parallel with your current model
  • Compare approval, default and fairness results

Step 3: Roll out

  • Expand product by product
  • Integrate with the loan origination system
  • Train staff on the new decisions and explanations
  • Keep monitoring the model and the regulations

Use Cases in Credit Risk Across Lending Products

Personal lending

  • Income verification for gig workers using bank transaction data
  • Debt-to-income calculations from current financial data

SME lending

  • Business cash flow analysis through transaction data
  • Seasonal revenue pattern identification

Credit cards and BNPL

  • Affordability checks at the point of sale
  • Credit limit changes based on usage, with clear reasons
  • Early warning of potential delinquency

The Future of AI Credit Scoring

Credit bureaus are adding more data too. Newer scores such as FICO Score 10T and VantageScore 4.0 use trended data, which looks at how balances change over time rather than a single snapshot. Open banking makes cash-flow data easier to use with the customer's consent.

The lenders that benefit most will pair better models with strong explanations, bias testing and monitoring.

Summary: AI Credit Scoring

AI credit scoring can score borrowers that traditional models miss, but only if every decision can be explained and the model is tested for bias. Start with a pilot on thin-file applicants, measure against your current scorecard, and keep compliance involved from day one.

Codiste is an AI agent development studio that builds explainable credit models and lending agents for funded fintech founders and CTOs. Schedule a consultation to talk about your lending workflow.

Portrait of Nishant Bijani, CTO and Co-Founder of Codiste

Nishant Bijani

CTO & Co-Founder | Codiste

Nishant builds where ambitious ideas meet production reality. As CTO & Co-Founder at Codiste, he has helped ship 150+ AI systems. Through The CTO Story, he gets technical leaders talking about what rarely makes the slide deck: the trade-offs, failures, and decisions behind what actually ships.

Relevant blog posts

What Are AI Agents and Agentic Workflows?
Artificial Intelligence
June 12, 2024

What Are AI Agents and Agentic Workflows?

Measuring KPIs for AI Marketing Tool Performance and Business Success
Artificial Intelligence
February 13, 2025

Measuring KPIs for AI Marketing Tool Performance and Business Success

Talk to Experts About Your Product Idea

Every great partnership begins with a conversation. Whether you're exploring possibilities or ready to scale, our team of specialists will help you navigate the journey.

Contact Us

Phone